The Ultimate Guide to Welders’ Insurance: Managing Risk for Your Metal Fabrication Business
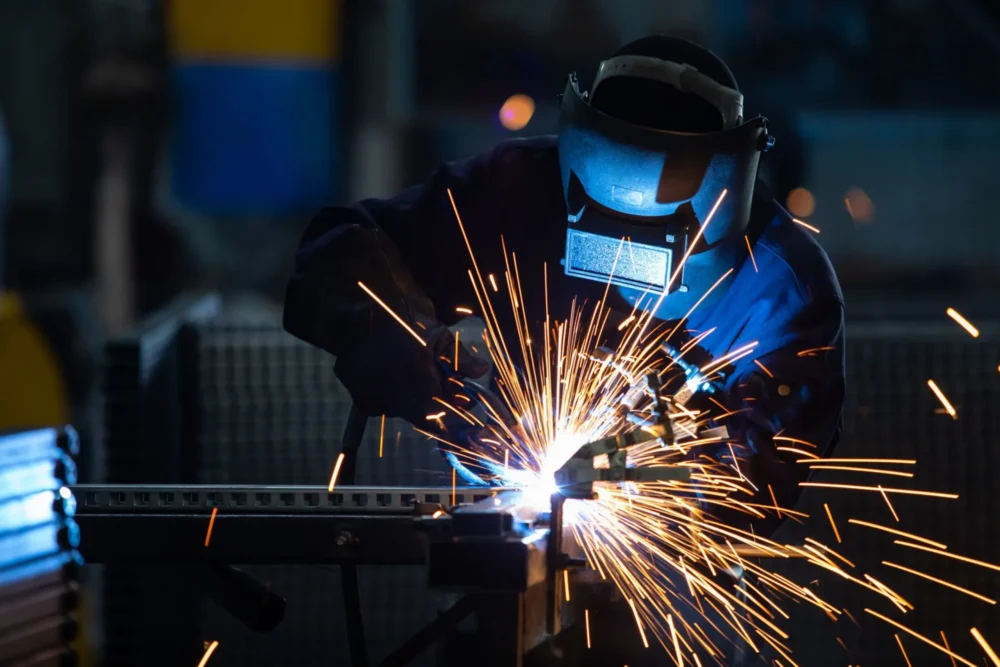
For professional welders, precision is everything. A single millimeter can differentiate a flawless structural weld from a catastrophic failure. However, even if your technique is immaculate, operating a welding, brazing, or cutting business can expose you to intense, high-temperature risks every single day.
From open flames and stray sparks that can ignite major structural fires to heavy machinery injuries and specialized equipment theft, the exposures can be extensive. Without the right commercial coverage, a single unexpected incident can derail your business.
At Midwest Select Insurance Group (MSIG), our experienced team can help you manage complex risk profiles and identify insurance options designed to help protect your business. This guide breaks down exactly what welders’ insurance is, why it’s often required, essential coverage options, and how to compare competitive rates without sacrificing appropriate coverage.
What is Welders’ Insurance?
Welders’ insurance is not a singular, off-the-shelf policy. Instead, it is a combined suite of commercial insurance policies designed to help protect independent welding contractors, mobile rigs, and structural steel fabrication shops from the unique financial liabilities that can arise when working with extreme heat, pressurized gases, and heavy metals.
Whether you run a mobile repair truck servicing agricultural equipment or manage a large-scale industrial fabrication shop, your risk environment can differ drastically from that of standard contractors. A typical, generic artisan contractor policy often contains strict exclusions regarding hot work, structural steel, or multi-story operations. A dedicated welder’s insurance program may help address coverage gaps that are common in welding operations.
Why Do Welders Need Specialized Insurance?
Many general contractors or property owners require proof of insurance before allowing work on a job site. Providing a Certificate of Insurance (COI) is a standard prerequisite for bidding on commercial projects.
Beyond contract compliance, the physical and financial risks of welding are inherently high:
Fire Risk (The “Hot Work” Factor)
Sparks and slag can fly up to 35 feet from the work area. They can smolder undetected in walls or insulation for hours before erupting into a full-scale structural fire.
Property Damage
Working on a client’s high-value property or heavy equipment means you can be legally liable if your torch or grinder damages their assets.
Third-Party Injuries
Flash burns (arc eye), respiratory issues from toxic fumes, or tripping hazards from mobile leads can impact clients, bystanders, or other subcontractors visiting your work area.
High-Value Equipment
Your welding machines, plasma cutters, generators, and rigs represent tens of thousands of dollars in capital investment. If they are stolen from a job site or damaged in transit, replacing them out of pocket could freeze your cash flow.
Core Coverages for Welding and Fabrication Businesses
To build an effective risk management shield, your commercial insurance package should consist of several foundational components.
Commercial General Liability (CGL) Insurance
This is the absolute baseline of any business insurance plan. Commercial General Liability is designed to help protect your business if you are held legally responsible for third-party bodily injury or property damage.
- Example of Property Damage: While doing structural modifications on a commercial building, a stray spark ignites nearby materials, causing $150,000 in fire damage. Your CGL policy can help cover the property repair costs and legal defense fees.
- Example of Bodily Injury: A customer walks into your fabrication shop, trips over a ground cable, and breaks their wrist. CGL can help cover their medical expenses and your legal defense if they file a lawsuit.
MSIG Pro-Tip: Watch out for “Designated Work” or “Hot Work” exclusions in cheap, generic online policies. At MSIG, we help align your general liability coverage with your specific welding methods (TIG, MIG, Stick, Plasma, Arc) to help avoid uncovered claims.
Completed Operations Liability
For welders, your liability doesn’t end when you pack up your gear and leave the site. Completed Operations coverage, typically bundled into your General Liability, can help protect you if a weld you completed fails months or years down the line, resulting in injury or property damage.
- Example: You weld a structural support beam for a mezzanine floor. Two years later, the weld fails, causing a partial collapse that damages the inventory below. Completed Operations helps manage the resulting financial liabilities.
Inland Marine Insurance (Tools & Equipment Coverage)
A standard commercial property policy often only protects tools while they are inside your primary shop or garage. Because mobile welding rigs travel constantly between job sites, you may need Inland Marine Insurance to help protect your gear while it’s in transit, parked at a job site, or stored away from your primary business location.
- What it can cover: Inland Marine Insurance is designed to help protect welding power sources, torches, gas cylinders, safety gear, and expensive consumables against theft, vandalism, and vehicle accidents.
Commercial Auto Insurance
If you operate a mobile welding rig, transport heavy tanks of oxygen and acetylene, or use a pickup truck to haul steel to job sites, a personal auto policy may not cover you in the event of an accident. You may need Commercial Auto Insurance.
This coverage offers higher liability limits and includes vehicles specifically modified for commercial use, including custom tool racks, heavy utility beds, and attached machinery.
Workers’ Compensation Insurance
If you hire helpers, shop hands, or apprentice welders, Workers’ Compensation is legally required in almost every state. It can help cover medical bills, lost wages, and rehabilitation costs if an employee is injured on the job.
Given the frequency of flash burns, lacerations, inhalation injuries, and heavy lifting strains in the metalworking industry, robust workers’ comp coverage helps manage financial risk associated with employee injury lawsuits.
Commercial Property Insurance
If you own or lease a permanent brick-and-mortar fabrication shop, commercial property insurance is designed to help protect the physical building, office equipment, heavy fixed machinery (like CNC plasma tables, ironworkers, and industrial shears), and raw steel inventory against risks like fire, windstorms, and break-ins.

How Much Does Welder’s Insurance Cost?
Insurance premiums are highly individualized. No two welding businesses share identical risk profiles. When underwriting a policy, insurance carriers evaluate several core variables to calculate your premium rates:
Primary Cost Drivers for Welding Policies
| Risk Factor | Impact on Premium | Why It Matters |
| Industry Specialization | High | Welding structural elements on bridges, skyscrapers, or pressure vessels carries a much higher risk than light decorative or automotive welding. |
| Mobile vs. Shop-Based | Moderate | Mobile welders can face higher auto and tool transit risks; fixed shops can face higher building property and third-party foot traffic risks. |
| Annual Revenue & Payroll | High | Higher revenue and larger payrolls indicate a larger scale of operations, which can increase the statistical probability of a claim. |
| Geographic Location | Moderate | Local litigation environments, regional weather risks, and regional commercial property values often shift baseline rates. |
| Claims History | High | A clean record can indicate proactive safety management, qualifying your business for preferred tier pricing and discounts. |
Smart Strategies to Help Manage Your Insurance Premiums
Protecting your business shouldn’t break your operating budget. By implementing rigorous safety standards and selecting the right insurance partner, you can significantly reduce your premium costs:
Maintain a Strict “Hot Work” Safety Program
Insurance companies look favorably upon businesses that actively mitigate risk. This can include implementing and documenting a formal hot work permit system, maintaining fully charged and inspected fire extinguishers on every rig, and enforcing, for example, a mandatory 30-to-60-minute post-weld fire watch on all field sites.
Bundle Coverages with a BOP (Business Owner’s Policy)
If you operate a small-to-medium-sized welding operation with lower risk profiles, you may qualify for a Business Owner’s Policy (BOP). A BOP bundles General Liability, Commercial Property, and more into a single package. This can offer lower premiums than purchasing each policy independently.
Optimize Your Deductibles
Choosing a higher deductible (the amount you pay out of pocket per claim) will lower your monthly or annual premiums. However, it’s important that your chosen deductible aligns with what your cash flow can handle during an unexpected event.
Work with an Independent Specialist Like MSIG
Captive insurance agents sell policies from a single parent provider. As an independent insurance agency, we partner with a vast network of top-rated commercial carriers. This allows us to compare policy options across multiple markets, helping you find coverage options and competitive pricing.
At MSIG, we understand that your welding business faces complex risks. Our experienced team works with you to review your daily operations, client contracts, and safety protocols, offering options aligned with your business.
Don’t leave your commercial operation exposed to catastrophic property damage claims or costly legal battles; contact MSIG today.